Europe’s
Lighting Leaders: Where Will the Next Growth Come From?
By Lawrence Lin
Founder, Lighting Recipe Studio · Chair, GLGA
Former Global CEO, LEDVANCE
European industry perspective · Information cut-off: 7 September
2026
Europe’s lighting companies have become fluent in explaining
difficult markets. Weak construction, deferred investment, price
pressure and the contraction of conventional lamps recur throughout
their financial commentary. The responses are familiar too:
restructuring, simpler organisations, fewer products, asset disposals
and leadership changes.
These pressures are real. Protecting cash and restoring profitability
are essential responsibilities. Yet an uncomfortable question remains:
can the industry explain its next source of customer value as clearly as
it explains its recent decline?
Europe has built substantial expertise in optics, industrial design,
architectural specification and application engineering. That heritage
creates an opportunity, and a reasonable expectation of leadership.
Customers should be able to see what these capabilities will deliver
next—in their buildings, their working environments and their homes.
The concern is that a mature market can gradually become an excuse
for limited ambition. Energy efficiency and environmental responsibility
remain indispensable. They cannot, on their own, explain why a customer
should choose one competent supplier over another.
The next phase of growth will depend on meaningful research, better
products and reliable delivery. If established lighting businesses do
not turn those capabilities into solutions customers value, the brands
that organise lighting within intelligent homes and buildings may
increasingly come from elsewhere.
Author’s disclosure: I previously served as Global CEO of
LEDVANCE and as Senior Adviser, Asia Pacific, to Zumtobel Group, with
the latter appointment ending on 30 June 2026. This article reflects on
an industry whose management decisions I have also helped shape. Company
assessments below draw on the sources identified in the
references.
Financial
resilience is only part of the answer
Recent results show considerable variation. Some businesses have
improved profitability without much revenue growth. Others have expanded
into adjacent electrical products, while several major lighting groups
have experienced pressure on both sales and margins.
| Signify |
€6.704bn in 2023 to €5.765bn in 2025 |
Adjusted EBITA margin: 10.0% to 8.9% |
Whether connected products and services can offset the contraction
elsewhere |
| Zumtobel Group |
€1.127bn in FY2023/24 to €1.040bn in FY2025/26 |
Adjusted EBIT margin: 5.1% to 4.1% |
Different recovery prospects in luminaires and components |
| Fagerhult Group |
SEK8.560bn in 2023 to SEK7.891bn in 2025 |
Operating margin: 10.5% to 7.7% |
Whether a broad brand portfolio produces sufficient differentiation
and returns |
| Luceco |
£209.0m in 2023 to £271.4m in 2025 |
Adjusted operating margin: 11.5% to 12.5% |
How much growth comes from existing operations and how much from
acquisitions |
| F.W. Thorpe |
Approximately £175–177m across FY2023–FY2025 |
Statutory operating margin: approximately 15.8% to 18.3% |
How specialised delivery and service support profitability |
These are group figures, including international operations and,
in some cases, substantial non-lighting activities. Fiscal calendars and
profit definitions differ. The table compares each business with its own
earlier performance; it is not a ranking of comparable European lighting
margins. Sources: the company reporting resources listed below.
Low growth is not necessarily poor management. A mature business can
create considerable value through dependable cash generation and
disciplined investment. However, leadership also involves developing
future demand. A stronger margin after restructuring is welcome; it does
not establish that customers have acquired a new reason to buy.
Europe needs a
broader proposition for light
For building owners, the relevant decision is often whether an
upgrade justifies disruption, installation costs and a long-term
maintenance commitment. A more efficient luminaire helps, but the full
proposition includes design, compatibility, commissioning, reliability
and service.
Europe’s renovation agenda creates room for that broader offer. The
revised Energy Performance of Buildings Directive treats lighting and
building automation within the wider performance of technical building
systems. The commercial opportunity lies in helping owners achieve
workable improvements in existing buildings, where equipment from
different generations and suppliers must coexist. [1]
This calls for practical innovation. Can an installer commission a
system more quickly? Can an owner replace a failed component without
replacing the entire installation? Can lighting work reliably with other
building controls? Can a designer improve visual comfort while retaining
flexibility for future changes of use?
Environmental claims also need to become more tangible.
Repairability, durable components, documented material choices and
accessible maintenance can influence purchasing decisions when they
reduce lifecycle cost or uncertainty. Repeating a general commitment to
sustainability provides much less differentiation.
Price competition deserves the same scrutiny. It can reflect excess
capacity and purchasing pressure, but it can also reveal that buyers see
too little difference between competing offers. Management cannot
control the construction cycle. It can influence whether its products
remain interchangeable in the customer’s eyes.
Signify:
a connected installed base still needs an economic case
Signify illustrates the scale of the transition. Sales fell by
approximately 14% between 2023 and 2025, while its adjusted EBITA margin
declined from 10.0% to 8.9%. Free cash flow remained substantial: €586m
in 2023, €438m in 2024 and €440m in 2025. Cash provides capacity to
invest, but it does not remove the growth challenge. [2]
The reported connected light-point base increased from 124 million in
2023 to 167 million in 2025. This is an important measure of deployment,
but a cumulative installed base is not equivalent to recurring revenue
or a disclosed number of paying software customers.
The commercial test is whether connectivity improves retention,
supports additional services and produces acceptable returns after
development and support costs. The industry needs greater clarity on
those outcomes before treating connected volume as proof of a
transformed business model.
Signify’s June 2026 strategy set medium-term ambitions of 0–1%
comparable sales growth, approximately 10% adjusted EBITA margin and a
7–8% free-cash-flow margin. Those targets acknowledge a restrained
growth environment. They also make the quality of resource allocation
especially important. [39]
As Tempelman’s arrival from the energy sector brings experience
relevant to this broader agenda. His appointment creates an opportunity
to connect lighting expertise with building and energy requirements. The
evidence of success will come from execution, customer adoption and cash
returns. [3]
Zumtobel
and Tridonic: two recovery challenges within one group
Zumtobel’s results show why a group average can obscure the operating
task. In FY2025/26, lighting revenue declined by 3.7%, yet adjusted EBIT
rose from €51.3m to €54.7m. Components revenue fell by approximately
11%, with adjusted EBIT declining from €13.5m to €4.6m. The two
businesses require different responses. [4]
For professional luminaires, specification, design and application
support can help defend value. For components, technical differentiation
has to withstand demanding procurement processes and competitive
pricing. A driver or control device becomes more valuable when it
improves system performance or reduces integration effort; connectivity
alone does not ensure pricing power.
Heiner Lang joined the management board on 1 September 2026 and is
scheduled to become CEO on 1 October. His industrial automation
background is relevant to the group’s development, while preserving its
optical and application knowledge will remain essential. [5]
First-quarter FY2026/27 sales were €264.1m, down 0.9%, with adjusted
EBIT of €8.2m and a 3.1% margin. These results precede the incoming
CEO’s tenure and should be assessed accordingly. A leadership transition
can establish priorities, but recovery must be demonstrated over
subsequent reporting periods. [6]
Fagerhult,
Luceco and F.W. Thorpe: different routes to value
Fagerhult’s portfolio includes businesses built around architectural
specification, local professional markets and infrastructure. Its
revenue fell by approximately 7.8% between 2023 and 2025, and operating
cash flow declined from SEK1.209bn to SEK740m. Brand breadth has not
insulated the group from weaker demand. [7]
The acquisitions of Trato TLV and Capelon add exposure to specialised
applications and connected outdoor lighting. Their strategic logic is
understandable. Their long-term value depends on whether they improve
customer access and capabilities at a return that justifies the capital
invested.
Multiple brands can preserve local expertise and distinct
relationships with specifiers. They can also duplicate costs. The
relevant question is whether each business has a clear role and whether
shared resources make the portfolio more effective.
Luceco presents a different picture. Revenue and adjusted operating
profitability improved between 2023 and 2025, with free cash flow
reaching £30.4m in 2025. Its activities extend across wiring
accessories, LED lighting, EV charging and portable power. Acquisitions,
including D-Line and CMD, contributed to the expansion. These are the
results of a broader electrical-products business, not a measure of
organic lighting-market growth. [8]
Its experience makes adjacency worth studying. Products that share
customers, installation channels and engineering capabilities may offer
a credible route to expansion. Diversification becomes less convincing
when it merely increases the number of separate businesses management
must support.
F.W. Thorpe offers another model. Revenue remained broadly stable
across FY2023–FY2025, while statutory operating margins improved. In
FY2025, operating cash flow was £33.2m and cash plus short-term
financial assets reached £61.8m. [9]
Thorlux’s offer extends from surveys and design through installation,
commissioning and after-sales support. Continued development of
SmartScan connects product engineering with the practical operation of
installations. This is a concrete example of innovation within an
established specialism.
A useful vision does not require every lighting company to build a
universal platform. It can involve doing a demanding application
exceptionally well and making the customer’s work easier.
The
private companies complicate the story of decline
Europe’s lighting industry cannot be understood through a few listed
groups alone. Privately owned manufacturers and design businesses reveal
different investment choices. Their financial disclosure is often less
extensive, so historical scale and current operational developments need
to be distinguished.
TRILUX is a substantial example. DDW lists 2023 revenue of
approximately €696.4m, a historical scale reference rather than a
current audited performance assessment. More tangible recent evidence
comes from the company’s investment programme: a Polish production and
development site opened in September 2024 with approximately €32m
invested and designed capacity of up to one million luminaires annually.
[10] [11]
In July 2026, TRILUX announced more than €80m of investment over
three years at Arnsberg, covering its headquarters and production
modernisation. Ansorg and Oktalite had also been brought together within
TRILUX Retail. These are identifiable commitments of capital and
organisational effort. Their value will depend on utilisation,
development efficiency and customer demand, but they make a blanket
accusation of industry inactivity difficult to sustain. [12] [13]
SLV Lighting Group is pursuing integration across a different
portfolio. Its predecessor, nnuks, reported turnover above €230m in
2021. That figure establishes historical group scale; it is neither
current revenue nor the turnover of the SLV brand alone. [14]
The group’s 2025 sustainability report describes five brands—SLV,
Nordtronic, Novalux, unex lighting and Knightsbridge—and measures to
share procurement, logistics and sales capabilities. Nordtronic and SLV
are centralising purchasing and logistics, while SLV supports Novalux’s
expansion beyond Italy. Knightsbridge also participates in wiring
accessories. [15]
The strategic opportunity is to make a multi-brand group more useful
to installers and distributors through availability, range and service.
Public disclosure does not yet allow those changes to be translated into
a reliable assessment of recent group profitability.
ERCO demonstrates the importance of application-specific product
development. Its 2026 introductions include flexible linear track
lighting for offices, further wallwashing applications and developments
for display lighting. Those improvements address identifiable design and
use requirements. [16]
Its scale should nevertheless be described cautiously. A business
index lists approximately €81.8m for ERCO GmbH in 2024, without
sufficiently clarifying the consolidation boundary. The available
evidence does not confirm current global brand revenue above €100m. ERCO
belongs in the discussion for its professional significance, rather than
an assumed revenue threshold. [17]
FLOS combines an active design programme with the financial
complexity of a wider luxury-design group. An Italian company database
lists approximately €134.2m of 2024 revenue for FLOS S.p.A.; this is a
secondary summary of a legal entity’s accounts, not verified global
consolidated FLOS-brand turnover. Product launches continued through the
2025 and 2026 Milan design weeks. [18] [19]
At Flos B&B Italia Group, the first-half 2026 continuing-business
pro forma figures, excluding Louis Poulsen and Fendi Casa, show revenue
of €270.2m, down 6.5%, and adjusted EBITDA of €50.1m, down 17.5%. The
18.5% EBITDA margin is a group measure encompassing furniture and other
design activities; it must not be attributed to FLOS lighting alone.
[20]
The agreement to sell Louis Poulsen illustrates how ownership and
financing influence even highly regarded brands. Announced in June 2026,
the transaction was expected to close in the second half, subject to
approvals. A disposal can support debt reduction and a new ownership
horizon; it does not, by itself, establish that the brand has failed.
[21]
EGLO adds the mass-market decorative-lighting perspective. Its
official company profile reports €523m of revenue for 2024 across a
portfolio extending beyond lighting alone. Comparable profit and
cash-flow figures are not supplied alongside that disclosure. Scale is
clear; the quality of recent returns is less visible. [22]
Specialisation
and controls still offer room to grow
Glamox’s holding company, GLX Holding, reported preliminary 2025
revenue and other operating income of NOK4.447bn, down 0.9%, with
adjusted EBITA of NOK680m and a 15.3% margin. Orders increased by 4.9%,
while operating cash flow declined from NOK691m to NOK497m. These
different movements show why orders, earnings and cash need to be
considered together. [23]
Schréder, whose 2023 turnover was reported at €560m by EY, is
extending its outdoor-lighting position through the acquisition of NLS
Lighting, announced in April 2026. Local manufacturing and project
access in North America provide a plausible complement to its technical
capabilities. The transaction price was not disclosed. [24] [25]
Plejd is a useful counterexample to the assumption that
lighting-related markets offer little growth. Its 2025 net sales reached
SEK935m, up 41.1%, with an EBIT margin of 24.6%. Management described
the growth as organic and identified contributions from adjacent smart
products and international expansion. It should therefore be understood
as growth in a broader control and installation proposition, not simply
stronger demand for luminaires. [26]
Dexelance’s lighting activities also grew in 2025, reaching €34.3m
from €32.1m. This is a smaller segment within a broader design group,
but it reinforces the need to examine individual markets rather than
assume uniform contraction. [27]
Turnarounds need equally careful interpretation. Edison’s
company-commissioned research on Dialight reports higher group
underlying operating profit for the year to March 2026 despite lower
revenue. However, lighting-segment revenue and underlying profit before
central costs both declined. Improvement elsewhere in a group, or lower
overheads, should not automatically be presented as a recovery in
lighting demand. [28]
LEDVANCE
and Inventronics: ownership does not remove the European operating
challenge
Europe’s lighting ecosystem includes businesses with international
ownership, engineering teams, manufacturing and customers. Their
strategic significance rests on what they deliver in European
markets.
LEDVANCE retains substantial brand recognition, distribution
relationships and local operating capabilities. Its parent’s
product-line disclosure reports 2025 revenue of RMB9.25bn and a gross
margin of approximately 40%. These are worldwide product figures
reported in the parent’s currency, not European regional revenue or a
standalone operating margin. [29]
The first half of 2026 illustrates the importance of that
distinction. LEDVANCE product-line revenue was RMB4.326bn, down 1.12%,
while its gross margin fell to 39.82%, a decline of 2.80 percentage
points. Gross profit decreased by approximately RMB142m. The parent
group’s profit recovery therefore cannot establish a recovery in
LEDVANCE’s lighting operations. Separate product-line net profit and
cash flow were not disclosed. [30]
Large acquisition-related impairments in the parent’s 2025 accounts
also require care: a reduction in the carrying value of an
acquisition-related asset group is not an equivalent amount of annual
operating loss at LEDVANCE GmbH.
For European customers, the more immediate questions concern product
development, service and project execution. The acquisition of loblicht
adds professional project capabilities. LEDVANCE’s August 2026
management announcement emphasised European B2B and project activity,
alongside more efficient customer processes. [31]
Its renewables range raises a further strategic question. Lighting,
photovoltaics, inverters and storage can share some channels and
customers, but commercial synergies need evidence. Public product
availability does not establish material revenue or acceptable returns.
[32]
Inventronics faces a related task following its acquisition of the
former ams OSRAM digital-systems business in Europe and Asia. The
acquisition brought engineering, products and customer relationships,
but those assets still have to earn their returns. Its subsequent
transition from licensed OSRAM branding to Inventronics increases the
importance of its own product reputation and service continuity. [38]
[38] [38]
For both businesses, the European test is practical: customer
retention, competitive technical performance, reliable availability and
profitable execution. Ownership changes and portfolio expansion can
support those outcomes; they cannot substitute for them.
IKEA
and Kingfisher: the customer relationship is already broader than
lighting
The industry’s future competitors need not begin as specialist
luminaire manufacturers. Home-furnishing and home-improvement businesses
can place lighting inside a purchase journey customers already
understand.
IKEA reported worldwide retail sales of €44.6bn in FY2025, down
approximately 1%, while volumes and customer numbers increased by around
3% following price reductions. These figures cover the whole IKEA retail
system, including non-lighting activities; they say nothing directly
about lighting profitability. [33]
More significant for lighting strategy was IKEA’s November 2025
announcement of 21 Matter-compatible smart-home products, including 11
KAJPLATS bulbs, sensors and remotes. Its proposition brings connected
lighting into an accessible home-furnishing context. [34]
The competitive implication is an inference from that offer: a
retailer that helps people choose, install and use a system can become
the brand associated with the experience, while individual device
suppliers become less visible. Product launches alone do not establish
that IKEA has achieved this at scale or profitably.
Kingfisher offers another view of channel influence. In the year
ended 31 January 2026, group sales were £12.945bn and adjusted pre-tax
profit £560m. B&Q sales reached £3.971bn, with like-for-like growth
of 3.3%. Own exclusive brands represented 43% of group sales across
categories, including ranges such as GoodHome and LAP. That percentage
is not a lighting-market share. [35] [36]
The next quarter was less favourable for B&Q: sales fell 3% as
reported and 4.1% like for like, although e-commerce grew. Channel
ownership does not eliminate exposure to household spending and
renovation cycles. [37]
Neither IKEA nor Kingfisher provides enough separate lighting
information here to compare its lighting profitability with
manufacturers. Their strategic relevance is nevertheless clear: they
influence assortment, price, convenience and the customer relationship.
Lighting brands need to demonstrate what additional value they bring
within that environment.
Leadership
requires a commitment that customers can recognise
The evidence does not support a claim that European lighting
companies have stopped innovating. TRILUX’s investments, ERCO’s
application work, F.W. Thorpe’s systems and service, and Plejd’s
expansion all provide concrete counterexamples.
The sharper concern is whether those efforts are sufficient,
sustained and commercially effective. Research expenditure alone cannot
answer this. Companies differ in their development cycles, accounting
policies and mix of software, electronics and optical engineering.
A credible vision should identify the customer problem, the resources
committed and the conditions that will determine success. For a building
owner, that might mean lower lifecycle cost and more dependable
maintenance. For an installer, less commissioning time and fewer
callbacks. For a specifier, better visual performance and clearer
integration choices. For a household, an intuitive system that continues
to work as devices change.
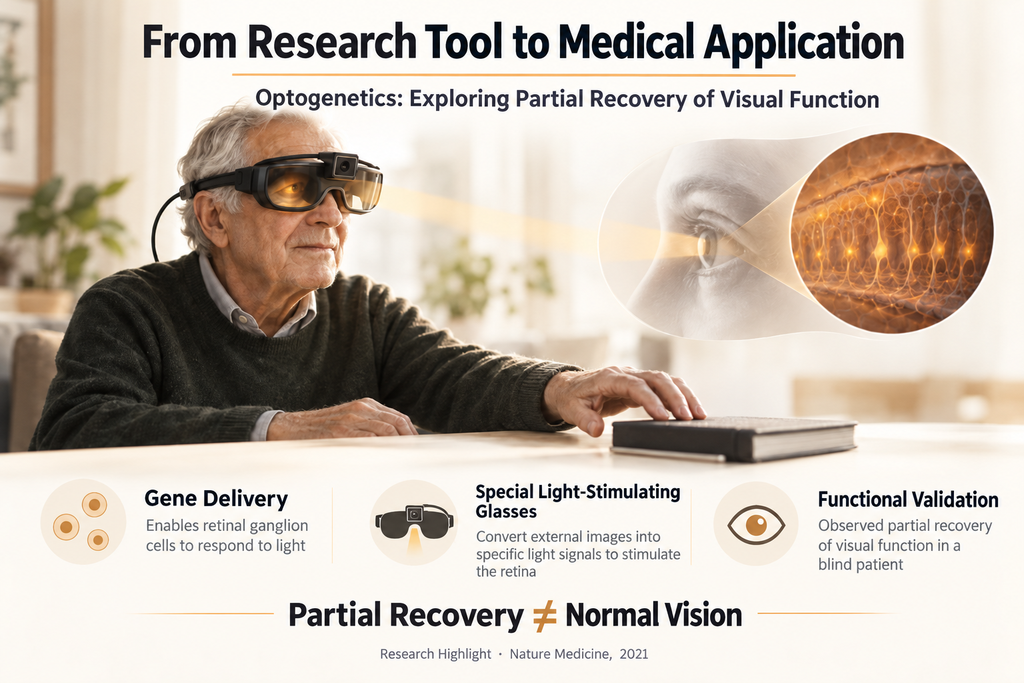
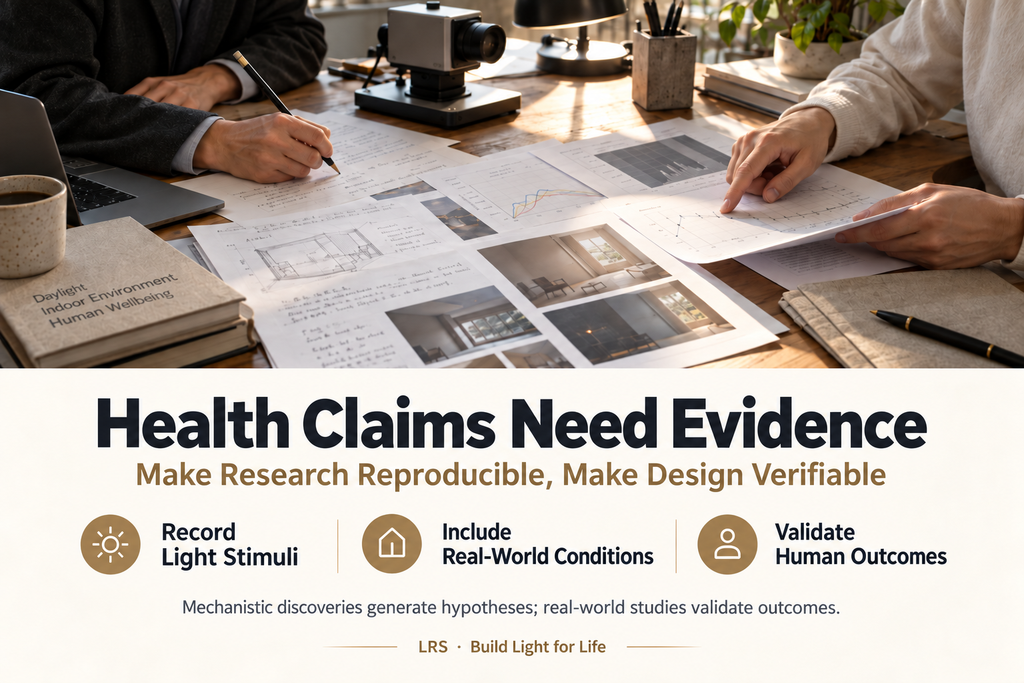
Claims about wellbeing should be tied to measured lighting conditions
and appropriate evidence. A controllable spectrum or a new product label
does not establish a health outcome. Professional credibility depends on
communicating what has actually been demonstrated.
Boards also need to examine what restructuring preserves. Repeatedly
reducing application engineering, software support and customer
knowledge may protect current earnings while weakening the next product
generation. Long-term projects require milestones and accountability,
but they also require continuity.
Europe’s strongest opportunity is to connect its existing expertise
with the realities of occupied buildings. That involves partnerships
with electrical, automation and building-service businesses; clearer
responsibility for commissioning and maintenance; and products designed
to remain useful within evolving systems.
Traditional lighting manufacturers still have substantial advantages
in optical performance, specification and application knowledge. New
entrants have their own execution gaps. The eventual outcome is
open.
What should concern established leaders is the possibility of
remaining technically capable while becoming commercially
secondary—supplying devices into systems whose customer relationships
and service revenues belong to someone else.
The next generation of European lighting leadership will be earned
through products and services that people can recognise as better,
supported by investment that produces durable returns. The question for
today’s leaders is whether their current decisions are building that
future.
Sources and reading notes
The references distinguish company financial reports, product
announcements and secondary scale estimates. Product and investment
announcements establish actions or intentions, not proven financial
returns. Figures retain their original currencies and reporting periods;
group, brand, legal-entity and product-line disclosures are not
interchangeable.
For readers using a platform that does not support external links,
copy the full address below into a browser. Some financial-report links
open PDFs; long addresses should be copied in full.
[1] EU Energy Performance of Buildings
Directive
Regulatory context for technical building systems; implementation and
scope depend on the relevant provisions.
https://eur-lex.europa.eu/eli/dir/2024/1275/oj
[2] Signify reporting and announcements
Company reporting archive; annual results supply the historical group
figures.
https://www.signify.com/global/our-company/news/press-releases
[3] Signify: CEO appointment
Background and timing of As Tempelman’s appointment.
https://www.signify.com/global/our-company/news/press-releases/2025/20250528-signify-names-as-tempelman-as-chief-executive-officer
[4] Zumtobel Group corporate information
Company reporting and announcements; group and segment measures must be
distinguished.
https://z.lighting/en/group/investor-relations/
[5] Zumtobel: Heiner Lang appointment
Board entry and planned CEO succession dates.
https://z.lighting/en-gb/group/news-insights/ir/supervisory-board-appoints-heiner-lang-ceo-zumtobel-group/
[6] Zumtobel Q1 FY2026/27 results
Quarterly figures preceding the incoming CEO’s tenure.
https://z.lighting/documents/4085/Zumtobel_Group_-Press_releases-_Q1_2026-27.pdf
[7] Fagerhult investor information
Annual reporting, portfolio and acquisition information.
https://www.fagerhultgroup.com/investors/
[8] Luceco investor information
Group reporting includes electrical products beyond lighting.
https://www.lucecoplc.com/investors/
[9] F.W. Thorpe annual report 2025
Financial results, SmartScan and operating model.
https://www.fwthorpe.co.uk/pdf/fw-thorpe-annual-report-2025.pdf
[10] TRILUX company profile, DDW
Secondary historical revenue estimate for 2023.
https://die-deutsche-wirtschaft.de/unternehmen/trilux-gmbh-co-kg-arnsberg/
[11] TRILUX sustainability report 2023/24
Polish facility investment and capacity; pages 36–37.
https://www.trilux.com/fileadmin/Downloads/Documents/Nachhaltigkeit/Sustainability_Report_2023-2024.pdf
[12] TRILUX Arnsberg investment announcement
Planned investment over three years, announced July 2026.
https://www.trilux.com/de/blog/neubau-standort-arnsberg/
[13] TRILUX Retail integration
Brand and organisational changes.
https://www.trilux.com/ch/blog/trilux-retail-migration/
[14] nnuks sustainability report 2022
Historical 2021 multi-brand group turnover.
https://slv-lighting-group.com/wp-content/uploads/2022/06/NKS_BRO_Sustainability-2022_210x279.pdf
[15] SLV Lighting Group sustainability report
2025
Brand portfolio and procurement, logistics and sales integration; pages
8–11.
https://a.storyblok.com/f/113144/x/f85bebdba1/slg_bro_sustainability-2025_210x279mm_72dpi.pdf
[16] ERCO new products
Application and product information; not financial evidence.
https://www.erco.com/en/products/new-products/
[17] ERCO business-index profile
Secondary legal-entity figure with an unclear consolidation
boundary.
https://www.weltmarktfuehrerindex.de/profil/erco
[18] FLOS S.p.A. company-account summary
Secondary transcription of legal-entity accounts, not global brand
revenue.
https://www.reportaziende.it/flos_societa_per_azioni_bs_00290820174
[19] FLOS at Milan Design Week 2026
Product-development evidence.
https://flos.com/en/wo/flos-at-milano-design-week-2026.html
[20] Flos B&B Italia Group H1 2026
presentation
Continuing-business pro forma results, pages 5 and 12; includes
non-lighting businesses.
https://www.flosbebitaliagroup.com/on/demandware.static/-/Library-Sites-DHCorp-contentlib/default/dw8ee7cc40/Investors/Reports%20and%20publications/1_presentation_Flos%20B%26B%20Italia%20S.p.A.%20-%20H1%202026_last.pdf
[21] Louis Poulsen transaction: buyer’s
adviser
Announced transaction subject to completion conditions.
https://accura.dk/en/cases/chr-augustinus-fabrikker-acquires-louis-poulsen/
[22] EGLO official company profile
Self-reported 2024 scale; no matching profit or cash-flow
disclosure.
https://lu.linkedin.com/company/eglo-leuchten-gmbh
[23] GLX Holding preliminary 2025 results
Holding-company reporting scope and preliminary results.
https://www.glamox.com/news-and-stories/glx-holding-as-the-holding-company-of-glamox-closes-2025-with-improved-profitability-and-robust-performance/
[24] EY profile of Schréder
Historical 2023 turnover, published December 2024.
https://www.ey.com/en_be/newsroom/2024/12/schreder-named-l-entreprise-de-l-annee-2024
[25] Schréder acquisition of NLS Lighting
Announced April 2026; price not disclosed.
https://www.schreder.com/en/news/schreder-announces-acquisition-nls-lighting
[26] Plejd year-end report 2025
Reported growth, profitability and management explanation of organic
expansion.
https://news.cision.com/plejd/r/year-end-report-2025,c4296913
[27] Dexelance investor presentation, April
2026
Lighting-segment revenue, page 25.
https://dexelance.com/wp-content/uploads/Investor-Presentation-DEXELANCE_v.-08.04.2026-FINAL-1.pdf
[28] Edison research on Dialight
Company-commissioned external research; group and lighting-segment
results on pages 3–4.
https://static.lse.co.uk/research/download/3653.pdf
[29] MLS annual report 2025
Listed parent’s product-line and acquisition-accounting disclosures, in
Chinese.
https://money.finance.sina.com.cn/corp/view/vCB_AllBulletinDetail.php?id=12234150&stockid=002745
[30] MLS interim report 2026
Product-line gross profit and consolidated group results, in
Chinese.
https://money.finance.sina.com.cn/corp/view/vCB_AllBulletinDetail.php?id=12563625&stockid=002745
[31] LEDVANCE management announcement, August
2026
Management responsibilities and European operating priorities.
https://www.ledvance.com/en-uk/company/press/press-releases/2026/ledvance-strengthens-its-management-team-with-dr-markus-emmert-n479050
[32] LEDVANCE Renewables announcement
Product range and stated strategy, not separate financial results.
https://www.ledvance.com/en-int/company/press/press-releases/2024/ledvance-introduces-ledvance-renewables–photovoltaics-for-a-brighter–greener-future-n303994
[33] IKEA FY2025 retail sales
Worldwide retail-system figures, not lighting-segment results.
https://www.ikea.com/global/en/newsroom/corporate/ikea-retail-sales-fy25-251016/
[34] IKEA smart-home product announcement
November 2025 Matter-compatible range.
https://www.ikea.com/global/en/newsroom/retail/the-new-smart-home-from-ikea-matter-compatible-251106/
[35] Kingfisher annual report 2025/26
Group and B&Q financial results; fiscal year ended January
2026.
https://www.kingfisher.com/~/media/Files/K/Kingfisher-Plc/Universal/investors/result-reports-presentation/2026/2526-annual-report-and-accounts.pdf
[36] Kingfisher own exclusive brands
43% relates to group sales across categories, not lighting alone.
https://www.kingfisher.com/our-banners-and-brands/own-exclusive-brands
[37] Kingfisher Q1 2026/27 update
Quarter ended April 2026; separate period from annual results.
https://www.kingfisher.com/~/media/Files/K/Kingfisher-Plc/Universal/investors/result-reports-presentation/2026/2026-27-q1-trading-update.pdf
[38] Inventronics annual reporting and acquisition
information
Company disclosures concerning acquired operations and subsequent
performance; source in Chinese.
https://cn.inventronics-co.com/news_info/33/1771.html
[39] Signify strategy announcement, June 2026
Medium-term growth, profitability and cash-flow targets are management
objectives, not reported outcomes.
https://www.signify.com/global/our-company/news/press-releases/2026/20260623-signify-introduces-strategy-to-create-a-more-focused-better-performing-company





 English
 Chinese (Taiwan)
 Chinese (China)
 German